A Homeowner's Guide to Navigating Roof Replacement Insurance Claims
When a severe storm rolls through Akron, the immediate aftermath can be incredibly stressful for homeowners. You might walk outside to find shingles scattered across your yard, perhaps even blowing into the Devil's Strip by the street. Suddenly, your focus shifts from everyday life to the structural integrity of your home. The prospect of dealing with insurance companies, claims adjusters, and extensive home repairs is enough to make anyone anxious.
At Ironclad Exteriors Co., we understand exactly how overwhelming this process can feel. Your home is your most significant investment, and an aging or compromised roof leaves everything beneath it vulnerable. Unfortunately, the insurance claim process isn't always straightforward. Without the right guidance, homeowners can face delayed payouts, confusing terminology, and the lingering fear that their claim might be underfunded or denied entirely.
We built our company to provide a completely different experience. As a veteran-owned business, we approach every aspect of residential roofing with integrity, transparency, and a commitment to selfless service. Our goal is not just to replace your roof, but to be your advocate throughout the entire restoration process. In this guide, we will walk you through exactly what to expect when filing a roof damage insurance claim, how to work effectively with adjusters, and how to protect your property for years to come.
Recognizing Storm Damage and Understanding Your Coverage
One of the most frequent questions we hear from homeowners is whether their homeowners insurance typically covers roof damage from wind and hail. In most cases, the answer is yes. Standard policies generally cover damage caused by sudden, unpreventable events—often referred to as acts of God. When a severe Lake Effect storm brings driving rain, high winds, or heavy hail, the resulting damage is usually eligible for a claim.
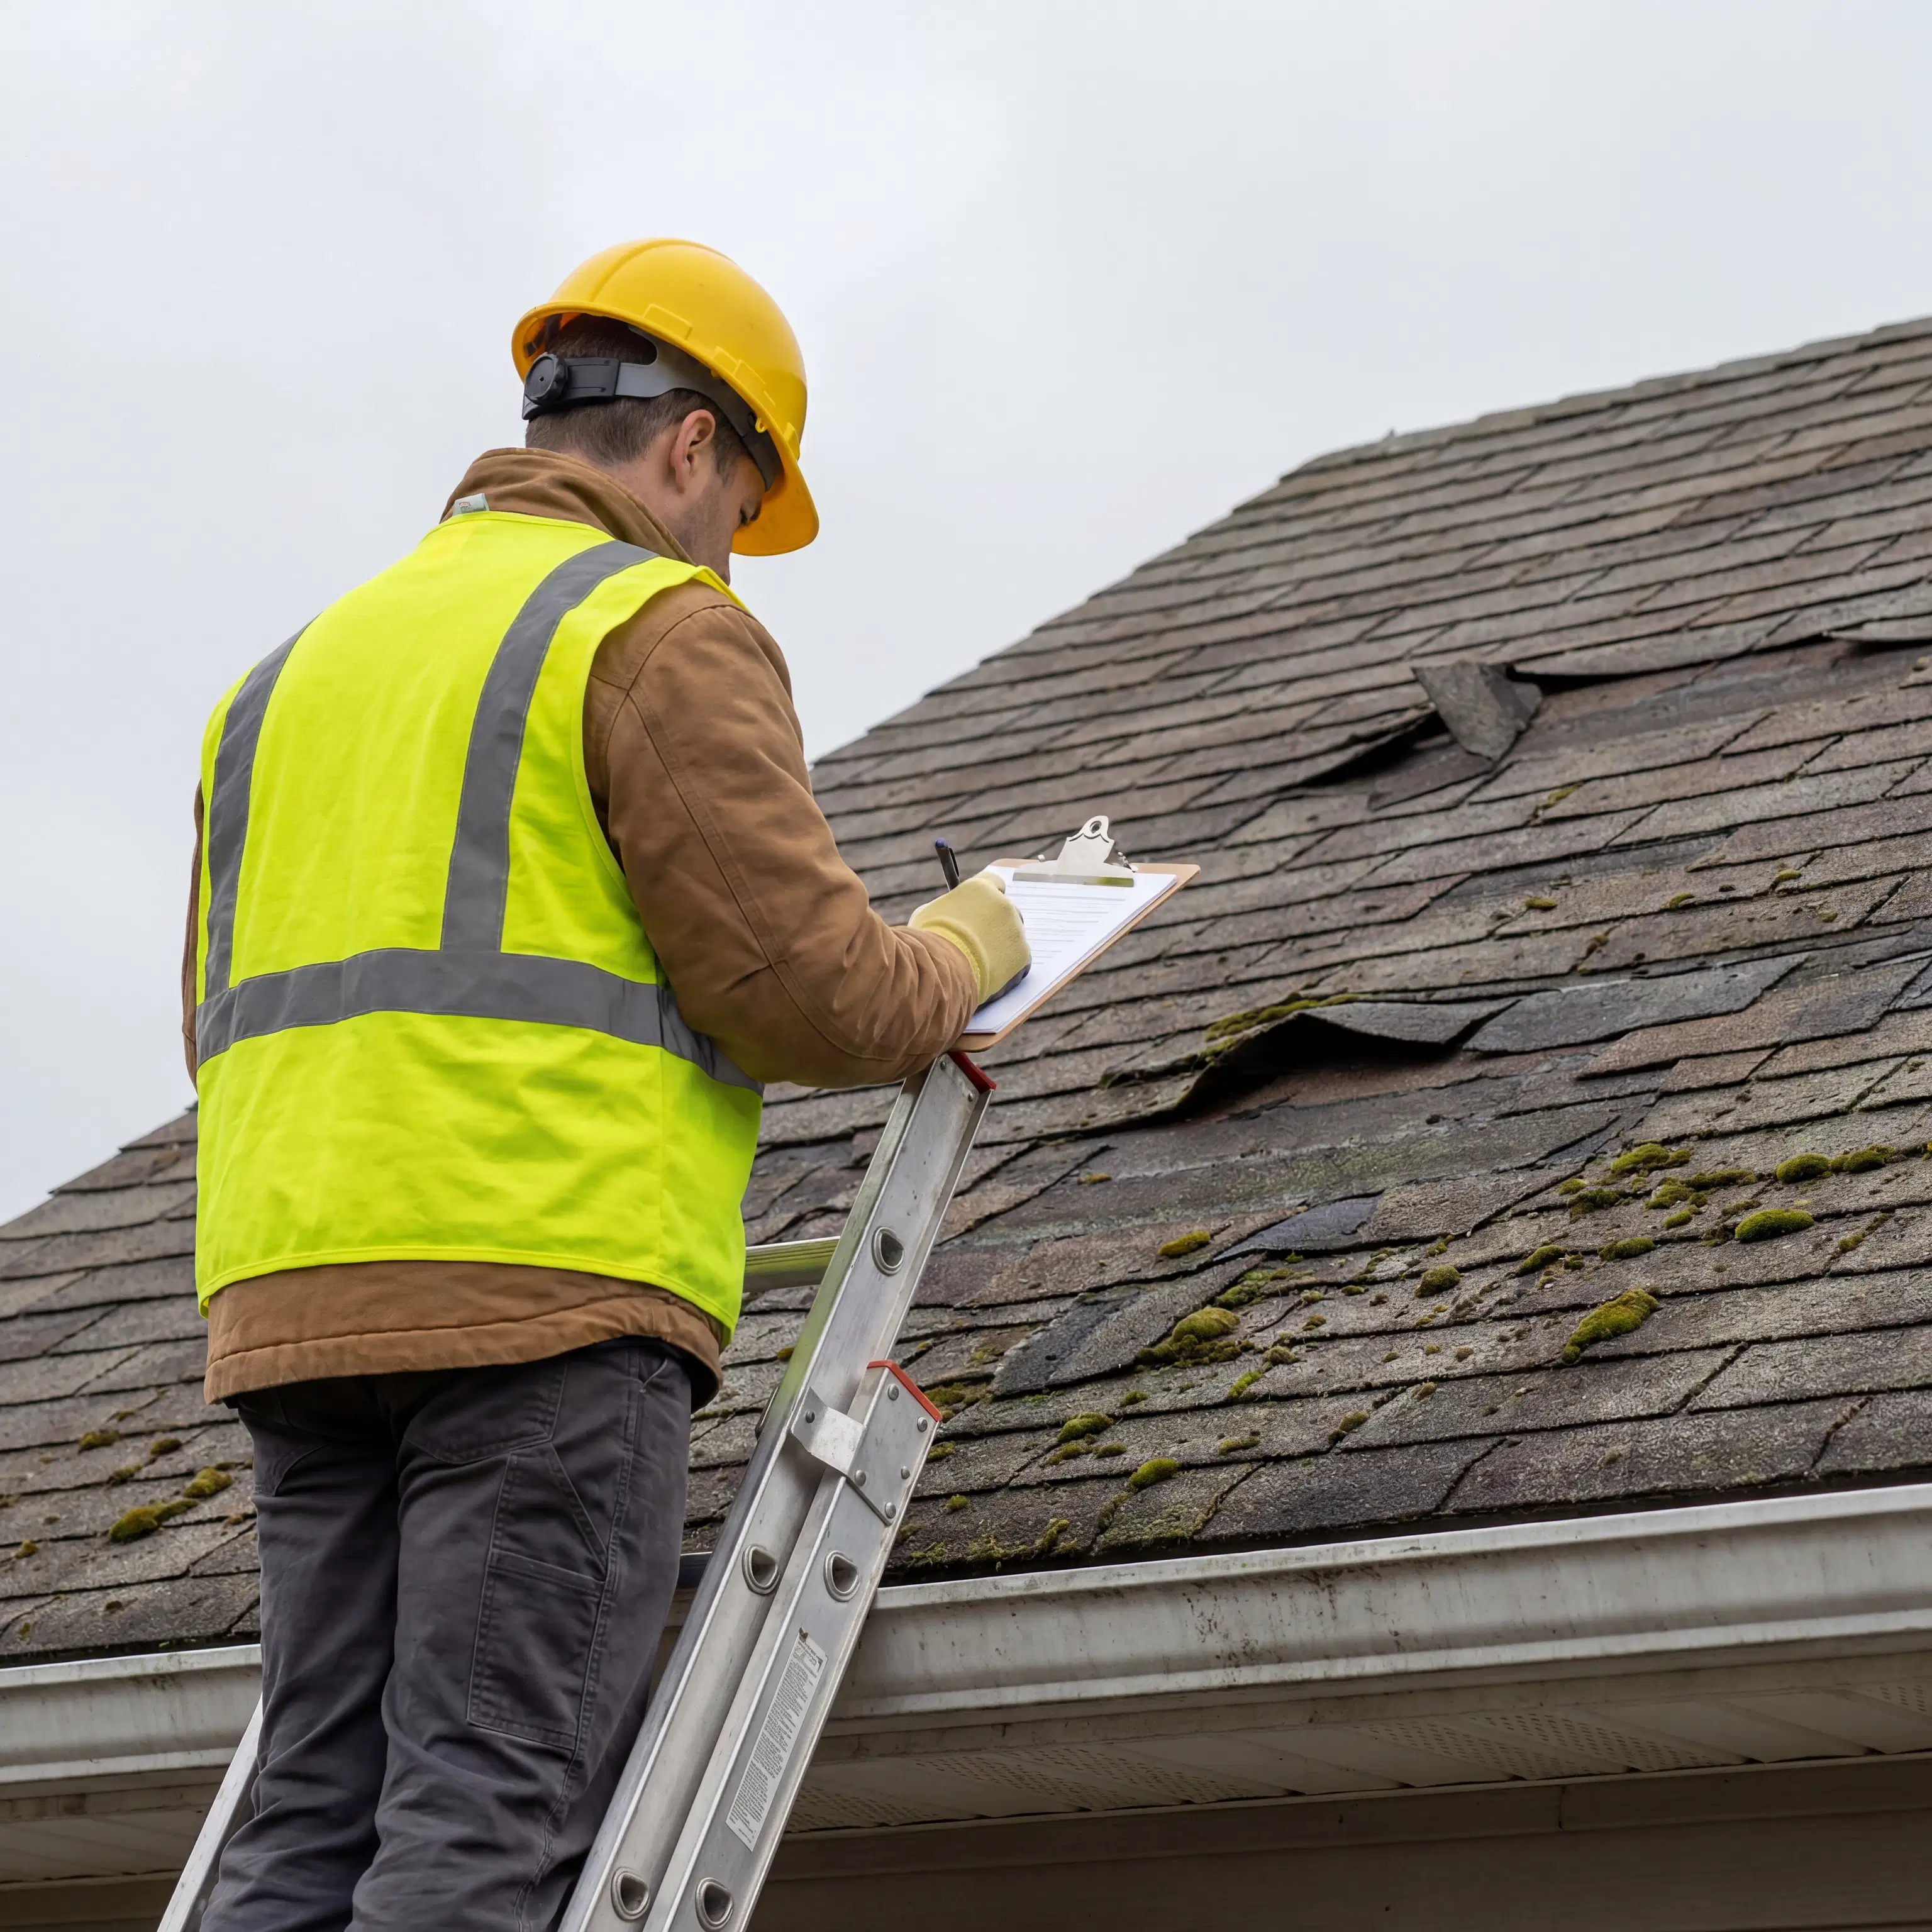
However, it is vital to act quickly. If you suspect damage, look for telltale signs from the ground: missing or torn shingles, dented gutters, or granules washing out of your downspouts. We strongly advise against climbing onto the roof yourself due to safety hazards.
Before you start the process, it is helpful to understand how your insurance company will value your claim. There are two primary types of coverage policies:
Actual Cash Value (ACV): If you have an ACV policy, the insurance company will calculate the cost to replace your roof and then subtract depreciation based on the roof's age. This means your payout will be lower than the actual cost of a new roof, and you will be responsible for covering the difference.
Replacement Cost Value (RCV): An RCV policy is much more favorable for homeowners. Under this policy, the insurance company pays for the total cost of replacing your roof with materials of comparable kind and quality at current market prices, minus your deductible. They often pay this out in two parts: an initial actual cash value payment, followed by the recoverable depreciation once the work is completed and invoiced.
Knowing which policy you hold is the first step in setting realistic expectations for your project budget and potential out-of-pocket costs.
How to File a Claim and Work With Insurance Adjusters
Navigating the claims process smoothly is crucial because delays in insurance claim processing can stall project starts, leaving your home exposed to further weather damage. Here is a clear, step-by-step approach to filing your claim and getting your restoration underway.
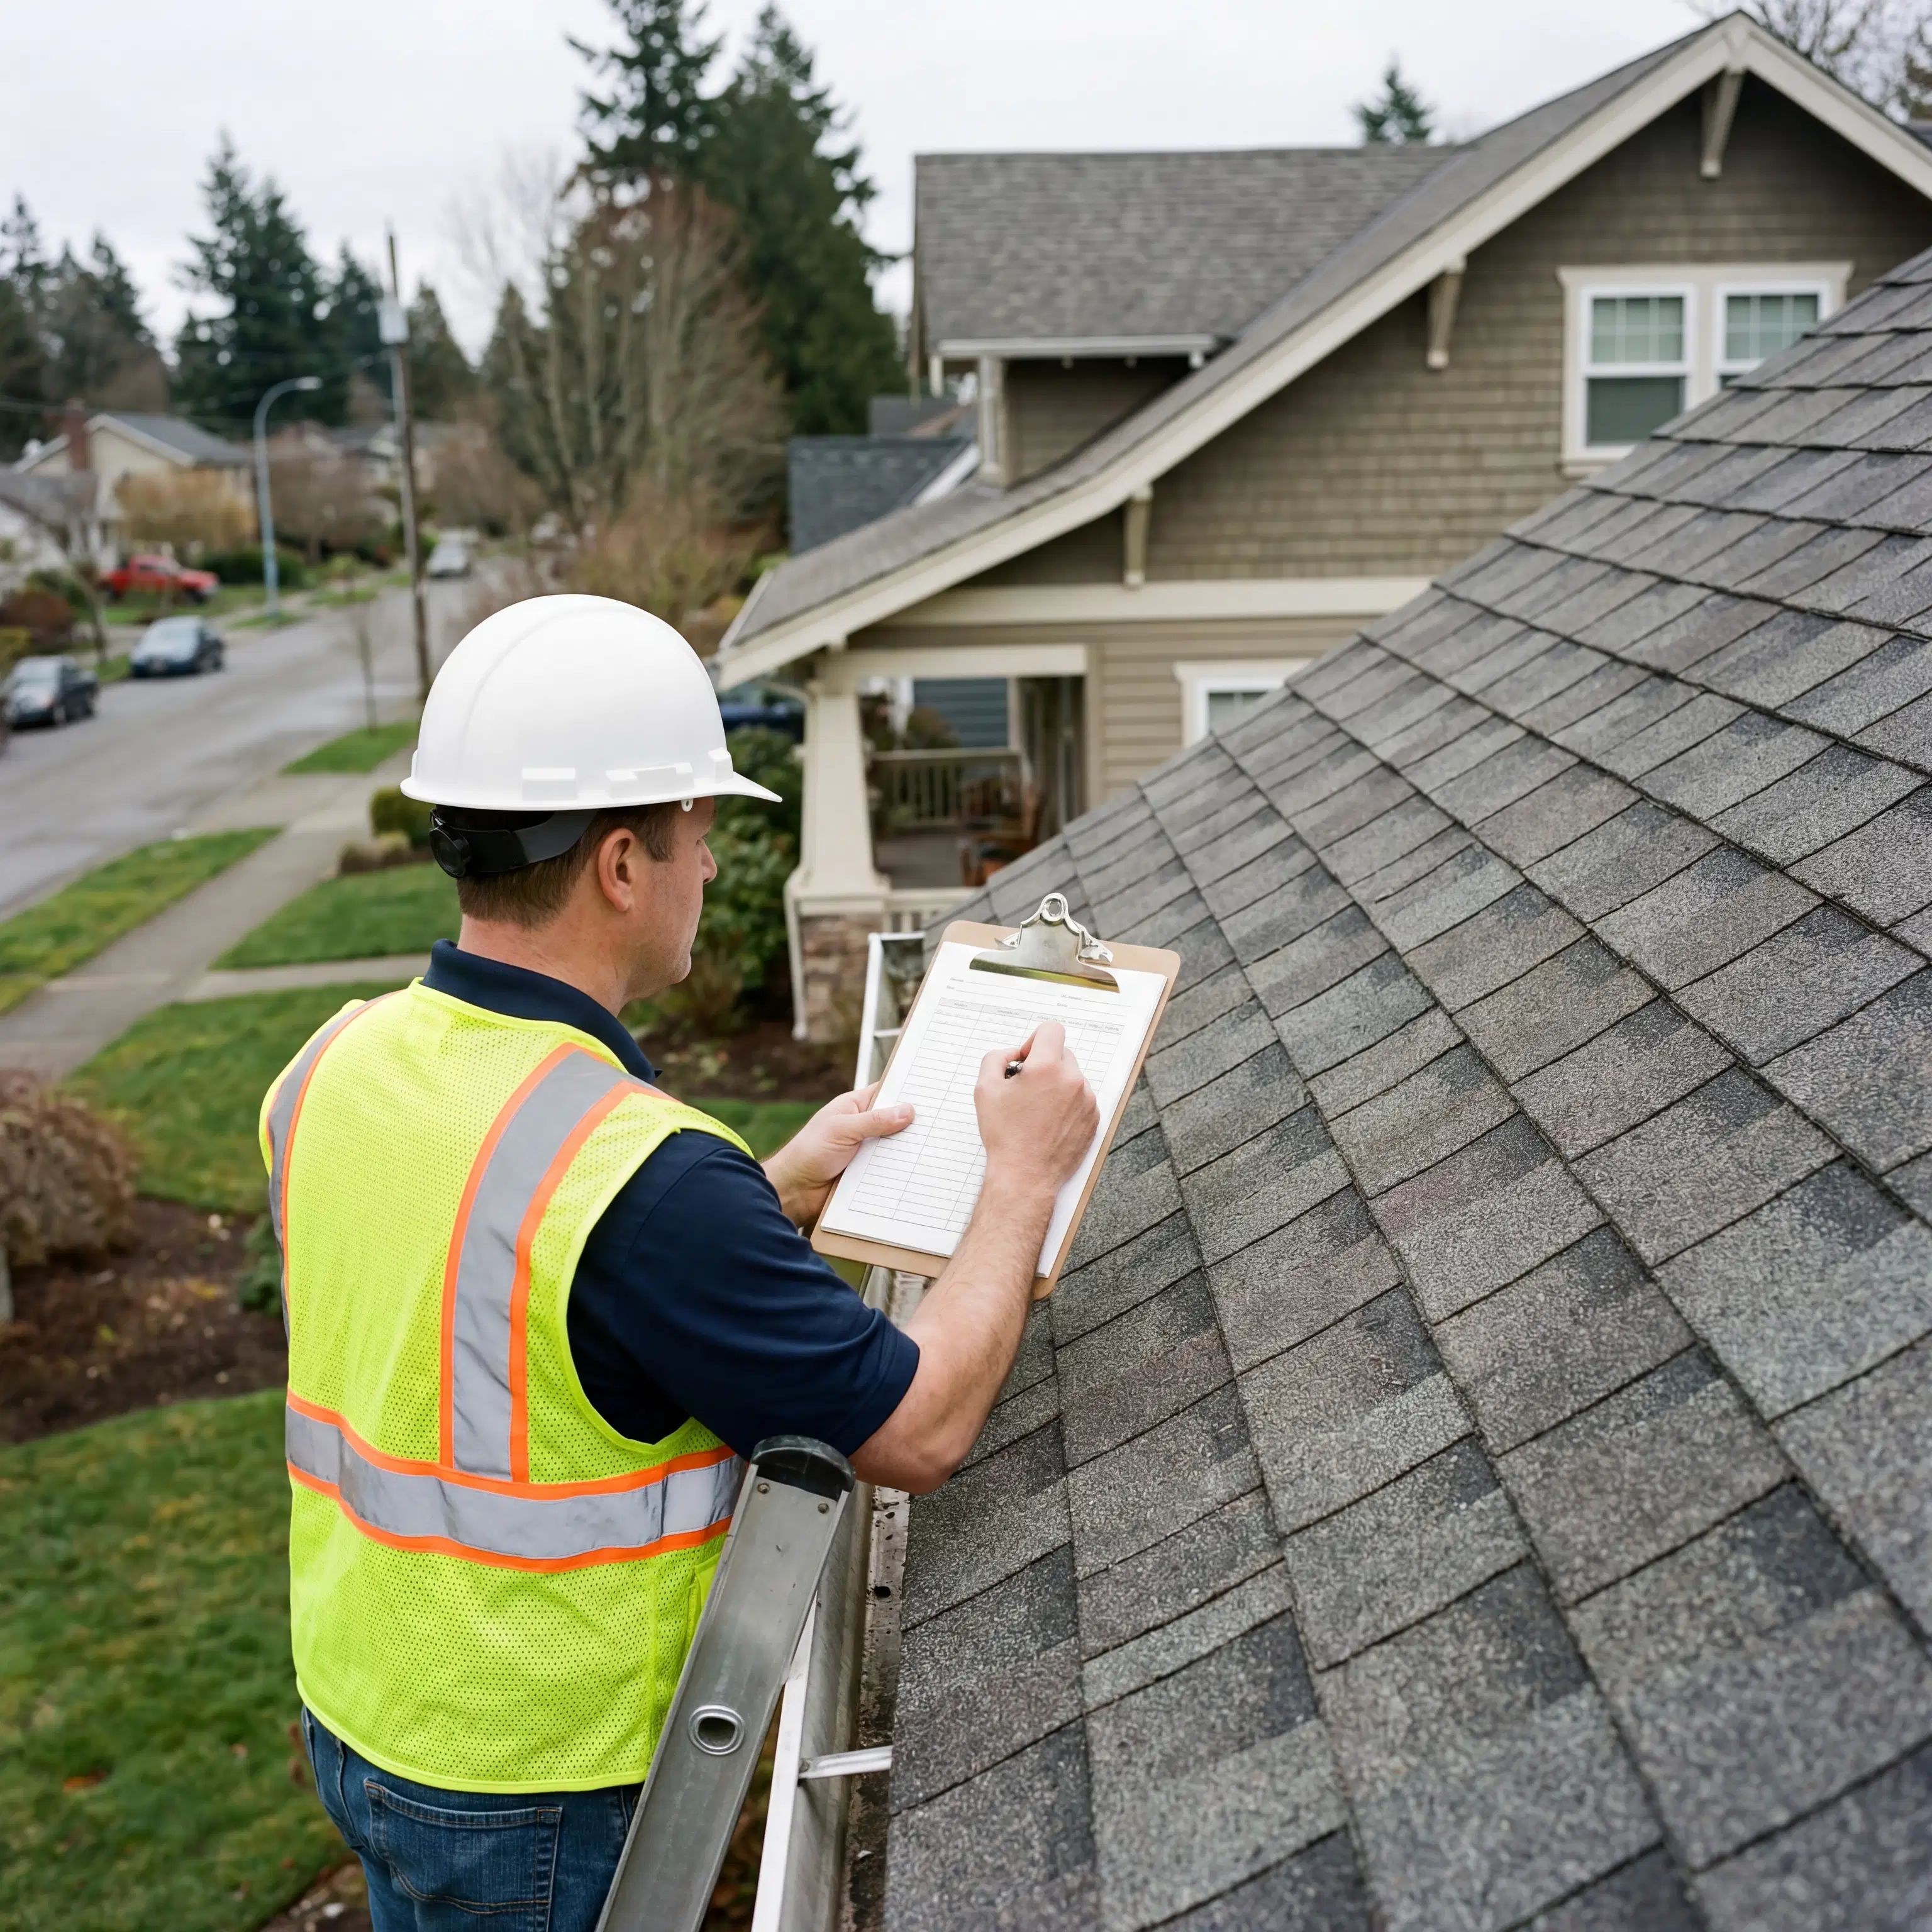
First, document everything you can see from the ground. Take wide photos of your property and close-ups of any visible damage, like debris or broken shingles. Next, contact a reputable, local roofing contractor for a comprehensive inspection before you call your insurance provider. At Ironclad Exteriors Co., we leverage advanced drone inspections to provide fast, contactless, and highly accurate damage assessments. This technology allows us to capture detailed, high-resolution evidence of hail strikes and wind damage that might be missed by the naked eye, ensuring your insurance company receives undeniable proof of the destruction.
Once you have our professional assessment, contact your insurance agent to officially file the claim. They will assign an insurance adjuster to evaluate your property. We highly recommend having your roofing contractor present when the adjuster arrives. Working with insurance adjusters requires speaking their language; our team can point out the specific structural damage we found, ensuring the adjuster's report is accurate and comprehensive. This collaborative approach dramatically reduces back-and-forth disputes and helps expedite your approval.
After the claim is approved, we provide a detailed proposal outlining the scope of work, materials, and timeline. Because we focus on complete roofing systems, we assess everything from proper attic ventilation to heavy-duty ice and water shields, ensuring your new roof meets all local building codes and manufacturer specifications.
Protecting Yourself from Storm Chasers
Following a major weather event, it is unfortunately common for out-of-state contractors—often called storm chasers—to flood the area. They knock on doors offering incredibly low prices or promising to waive your insurance deductible (which is actually insurance fraud). These companies often use high-pressure sales tactics, perform subpar work with cheap materials, and leave town as quickly as they arrived, leaving you with a faulty roof and no one to honor the warranty.
Homeowners in Northeast Ohio are rightfully skeptical of these traveling crews. The best way to protect your investment is to hire a contractor with deep, established roots in your community. When you work with a trusted team from the 330 area, you know exactly where their physical office is and who to call if you ever have a question down the road.
As a veteran-owned company, Ironclad Exteriors Co. operates strictly on military LDRSHIP values: Loyalty, Duty, Respect, Selfless Service, Honor, Integrity, and Personal Courage. We never cut corners. We install premium Owens Corning roofing systems designed specifically to withstand our harsh climate, and we back our complete roof replacements with an Ironclad 15-Year Workmanship Warranty. We believe in providing honest recommendations without any high-pressure sales tactics, allowing you to make the best decision for your family and your budget.

Taking the Next Step Toward Peace of Mind
Dealing with storm damage is undoubtedly stressful, but the restoration process doesn't have to be a nightmare. By understanding your insurance policy, thoroughly documenting the damage, and partnering with a reputable local contractor who utilizes modern inspection technology, you can navigate the process efficiently and confidently.
Don't let the anxiety of insurance paperwork prevent you from protecting your home. If you suspect your roof has sustained wind or hail damage, our dedicated team is here to help you manage your storm damage insurance claims from the initial drone inspection to the final cleanup.
Ready to get started? If you are a homeowner in Summit County looking for a roofing partner you can truly trust, contact us today or use our instant estimator to take the first step. Let Ironclad Exteriors Co. ensure your home is built strong and built to last.